Understanding Pension Pillars (I, II, III) in Lithuania
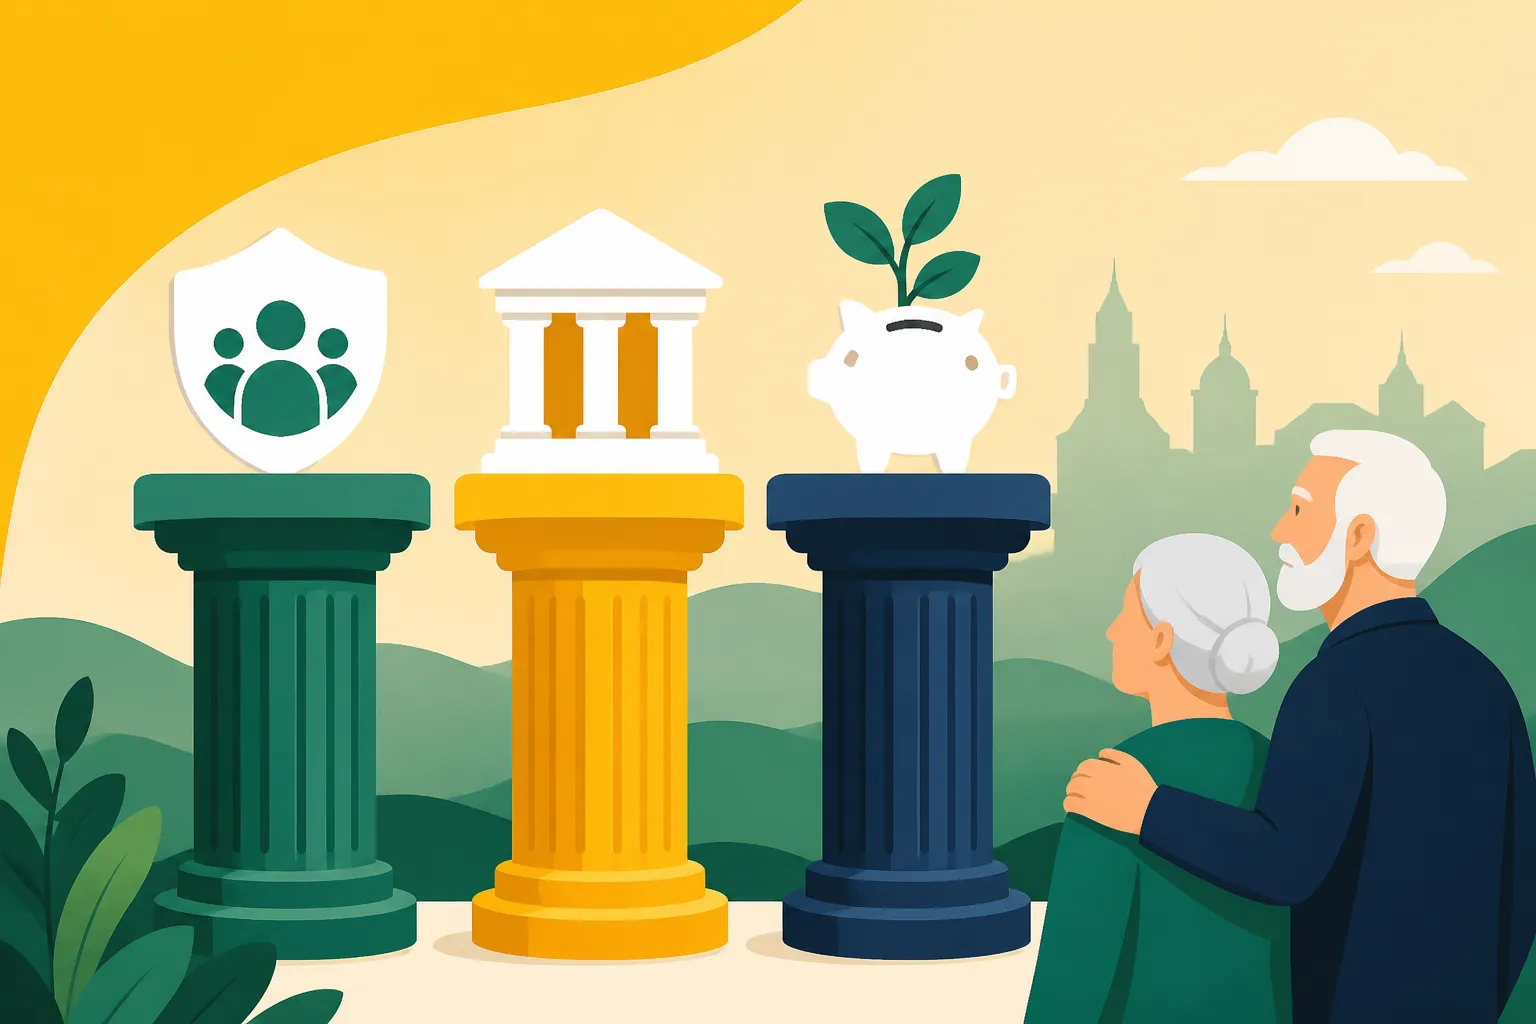
The Lithuanian pension system can feel like a labyrinth, especially when you're trying to figure out how your future retirement savings will work as an expat. Many of us arrive here, busy with work and setting up life, only to realize the local pension system has multiple "pillars" that aren't immediately clear. This guide is here to break down those complexities, explaining Lithuania's three-pillar pension system in detail, so you can make informed decisions about your financial future.
The Foundation: Pillar I (Valstybinio Socialinio Draudimo Pensija – State Social Insurance Pension)
When you first start working legally in Lithuania, whether employed or self-employed, you automatically become part of the compulsory state social insurance scheme managed by "Sodra" (Valstybinio socialinio draudimo fondo valdyba). This is your Pillar I pension, and it's the bedrock of the Lithuanian retirement system, designed to provide a basic level of income in your golden years. It's a "pay-as-you-go" system, meaning the contributions from today's workers fund the pensions of today's retirees.
How Pillar I Works: Mandatory Contributions and Eligibility
Pillar I is all about mandatory contributions. If you're an employee, a portion of your gross salary (before tax) is automatically deducted for social security, which includes contributions for your future Pillar I pension. Your employer also makes significant contributions on your behalf. These contributions are not "saved" in an individual account for you; instead, they go into the general Sodra fund. When you retire, your Pillar I pension amount will be calculated based on your length of service (how many years you contributed) and your average insurable income over those years.
For example, if you arrive in Vilnius and start a new job, you might initially focus on your net salary and what taxes you pay. But behind the scenes, both you and your employer are contributing to Sodra. These contributions are crucial for accumulating the necessary work periods (stažas) that determine your eligibility and the eventual size of your state pension. Without these contributions, which are meticulously recorded by Sodra, you wouldn't qualify for the full state pension, or perhaps any at all, once you reach retirement age. Understanding how Sodra social insurance contributions in Lithuania are calculated is vital for grasping your overall compensation package.
Who Contributes to Pillar I
Everyone who is legally employed or self-employed in Lithuania and earns above a certain threshold is generally obliged to contribute to Pillar I. This includes:
- Employees: As mentioned, contributions are deducted from your salary and supplemented by your employer's contributions. This is the most common scenario for expats moving here for work.
- Self-Employed Individuals: If you're registered for individual activity (individuali veikla) or operate a business certificate (verslo liudijimas), you're responsible for declaring and paying your own Sodra contributions. This requires a bit more proactive management than for employees, as there's no employer to handle it for you. It's critical to understand Understanding Sodra Social Insurance Contributions in Lithuania to ensure compliance and secure your future benefits.
- Certain State-Insured Individuals: In some cases, the state might cover contributions for certain groups, such as those receiving specific benefits, but for working expats, it's primarily tied to employment or self-employment.
It's important to differentiate this from other forms of social insurance. While your contributions cover not just old-age pension but also sickness benefits, maternity leave, and unemployment insurance, the pension component is what we're focusing on here. The system is designed to be comprehensive, but its core function is to ensure a basic safety net in retirement.
Benefits and Limitations of Pillar I
The main benefit of Pillar I is its universality and mandatory nature, ensuring that most working residents accrue some level of pension entitlement. It's a collective insurance scheme, providing a baseline income that is usually adjusted with inflation to maintain purchasing power. For someone planning to retire in Lithuania, it forms the predictable part of their retirement income.
However, Pillar I also has its limitations. Because it's a pay-as-you-go system, its sustainability is heavily dependent on demographics – the ratio of working contributors to retirees. If the birth rate declines and life expectancy increases, there are fewer workers supporting more retirees, which can strain the system. Furthermore, the payouts from Pillar I are generally modest, often not enough to maintain a comfortable lifestyle on their own. For many expats, especially those used to more robust state pensions or higher income levels, relying solely on Pillar I might not meet their retirement expectations. This is where the other pillars come into play, offering opportunities to supplement your state pension and secure a more comfortable financial future.
Boosting Your Future: Pillar II (Pensijų Kaupimas – Funded Pension Accumulation)
Pillar II is where things get a bit more dynamic and allow for personal choice in managing your retirement savings. Unlike Pillar I's collective fund, Pillar II involves individual, funded accounts held with private pension accumulation companies. It’s a hybrid system, combining elements of mandatory contributions with private fund management, aiming to provide a larger retirement pot than Pillar I alone.
The Opt-In/Opt-Out System and Its Evolution
Historically, Lithuania introduced a system where individuals could choose to direct a portion of their social insurance contributions from Sodra (Pillar I) into private pension funds (Pillar II), topped up by state and sometimes personal contributions. This system has evolved, notably with automatic enrollment.
Currently, if you're a new employee or a young person entering the workforce, you're often automatically enrolled into Pillar II. This means that a small percentage of your gross salary (the part that would normally go entirely to Pillar I) is diverted to a chosen private pension fund, usually with an initial default fund. You then have a window to either confirm your participation, choose a different fund, or opt out entirely. If you opt out, all your contributions revert back to Pillar I.
Many expats find this auto-enrollment feature both a blessing and a mild headache. It's great because it forces you to think about supplementary retirement savings, but if you're not paying attention, you might end up in a default fund you haven't researched. Understanding the implications of this choice is crucial for your long-term financial planning.
Choosing a Pension Fund: Providers and Considerations
Once you're enrolled in Pillar II, whether automatically or by choice, you'll need to select a pension fund. Lithuania has several reputable financial institutions that offer Pillar II pension funds, including major players like Swedbank, Luminor, and SEB. These banks and financial companies manage a variety of funds with different risk profiles, from conservative funds with lower potential returns but less volatility, to aggressive funds invested heavily in equities, offering higher potential returns but also higher risk.
When choosing a fund, you'll want to consider several factors:
- Your Age and Risk Tolerance: Younger individuals often choose more aggressive funds as they have more time to recover from market downturns. As you approach retirement, it's generally recommended to shift towards more conservative investments.
- Fund Performance: While past performance is no guarantee of future results, looking at historical returns can give you an idea of a fund manager's track record.
- Fees: All pension funds charge management fees. Even small differences in fees can significantly impact your total accumulation over decades.
- Diversification: How diversified are the fund's investments? A well-diversified fund is less exposed to the risks of any single asset or market.
It’s worth noting that if you're managing investments in multiple currencies or considering international transfers for your wider financial planning, services like Wise (formerly TransferWise) can be incredibly useful, though directly related to pension contributions, they are more for moving personal funds. When it comes to the technicalities of your pension, it's crucial to consult directly with the pension accumulation companies or an independent financial advisor.
How Pillar II Contributions Work
The contribution structure for Pillar II is a bit layered:
- Personal Contribution (from your gross salary): A small percentage (currently 3% for those fully participating) of your gross salary is deducted and directed to your chosen Pillar II fund. This percentage is part of the social insurance contribution that would otherwise go entirely to Pillar I.
- State Contribution: The state also contributes an additional amount on your behalf, currently calculated as 1.5% of the average national wage. This is a significant incentive to participate.
- Optional Additional Contributions: You can choose to make additional voluntary contributions to your Pillar II fund. This allows you to boost your savings beyond the mandatory and state contributions. These voluntary contributions often come with tax benefits, similar to Pillar III, making them an attractive option for those looking to maximize their retirement savings.
This combined approach – personal, state, and optional contributions – makes Pillar II a powerful tool for building a more substantial retirement fund. It's essential to keep track of these contributions, which you can usually do through your chosen pension fund provider's online portal or the Sodra system.
Key Advantages and Risks
Advantages:
- Higher Potential Returns: Unlike Pillar I, which is a defined benefit system, Pillar II funds are invested in financial markets. This means your savings have the potential to grow significantly over the long term, potentially outpacing inflation and providing a much larger sum at retirement.
- Individual Ownership: The funds accumulated in Pillar II accounts are your property. In case of death, they are usually inherited, offering an extra layer of security for your family.
- Diversification: It reduces your reliance solely on the state pension, spreading your retirement risk across two different systems.
Risks:
- Market Fluctuations: As Pillar II funds are invested, their value can go down as well as up. There's no guarantee of returns, and a significant market downturn closer to retirement could impact your final sum.
- Fees: While transparent, management fees can eat into your returns over many years. It's crucial to compare fee structures between different providers.
- Complexity: Choosing the right fund and understanding its investment strategy requires some financial literacy or professional guidance.
For expats, especially those who may not stay in Lithuania until retirement, the portability of Pillar II funds is also an important consideration. While not as straightforward as transferring funds between bank accounts, there are mechanisms, often through international agreements or tax implications, for managing these assets if you leave the country. This can be complex, and getting advice from a specialist in cross-border taxation, perhaps even an international service like Taxes for Expats, can be invaluable.
Taking Control: Pillar III (Savanoriškas Pensijų Kaupimas – Voluntary Pension Accumulation)
Pillar III is entirely voluntary and represents the most flexible and personalized approach to retirement savings in Lithuania. It's designed for those who want to take full control of their long-term financial planning, supplement their Pillar I and II benefits, and potentially benefit from significant tax incentives. Think of it as your personal booster rocket for retirement.
What is Pillar III: Voluntary Schemes and Products
Unlike the mandatory nature of Pillar I and the semi-mandatory Pillar II, Pillar III is a completely optional layer of saving. It encompasses a range of private pension schemes and life insurance products that individuals can choose to invest in. These are managed by private financial institutions – typically the same banks and insurance companies that offer Pillar II funds, such as Swedbank, Luminor, and SEB.
The key differentiator here is that you decide how much to contribute, how often, and which fund or product best suits your financial goals and risk appetite. There's no auto-enrollment, no state contribution (apart from tax relief), and no mandatory percentage of your salary involved. It's all about proactive personal finance.
Tax Incentives and Flexibility
One of the most attractive features of Pillar III is the tax relief it offers. In Lithuania, personal income tax (GPM) can be reduced by claiming a deduction for contributions made to Pillar III pension funds or certain life insurance products. This means that a portion of the money you contribute to Pillar III can be offset against your taxable income, effectively reducing your overall tax burden for the year. The maximum amount you can deduct each year is usually capped at a certain percentage of your taxable income or a specific monetary limit.
This tax benefit acts as a powerful incentive, making Pillar III contributions even more appealing. It's essentially free money from the taxman that helps your retirement savings grow faster. However, it's crucial to understand the specific rules and limitations of these tax deductions, which can sometimes change. Consulting with a tax professional or utilizing resources like Taxes for Expats can help you maximize these benefits correctly.
The flexibility of Pillar III also extends to withdrawals. While intended for retirement, some Pillar III products might offer more lenient withdrawal conditions compared to Pillar II, although early withdrawals might negate tax benefits or incur penalties. It's important to thoroughly read the terms and conditions of any Pillar III product you consider.
Different Types of Pillar III Products
The market for Pillar III in Lithuania is diverse, offering various products to suit different investor profiles:
- Voluntary Pension Funds: These are similar in structure to Pillar II funds but are entirely voluntary. You choose a fund based on its investment strategy (conservative, balanced, aggressive) and make regular or lump-sum contributions. The funds are managed professionally, and their value fluctuates with market performance.
- Life Insurance Products with Savings Components: Many insurance companies offer life insurance policies that combine a life cover with an investment or savings element. A portion of your premium goes towards ensuring your life, while another portion is invested, growing over time to provide a payout at a specified future date or upon retirement. These products can be attractive for those looking for both protection and long-term savings.
- Other Investment Vehicles: While less common under the direct "Pillar III" umbrella, other long-term investment accounts, stocks, bonds, or real estate investments also serve as voluntary retirement savings, albeit without the specific tax benefits tied to dedicated pension or life insurance products.
The choice largely depends on your individual goals, risk tolerance, and how much active management you're willing to undertake. For a hands-off approach with tax benefits, voluntary pension funds are often preferred. If you also need life protection, an insurance-linked product might be more suitable. Regardless of the choice, Pillar III offers a vital avenue for building substantial wealth for your retirement, complementing the more structured Pillars I and II.
Navigating Your Pension Options as an Expat
As an expat in Lithuania, understanding these pension pillars isn't just an academic exercise; it's a critical part of your financial planning. Your unique situation – how long you plan to stay, your country of origin, and your career path – will heavily influence how you should approach each pillar. Ignoring them can lead to unpleasant surprises down the line.
Determining Your Eligibility and Entitlements
Your eligibility for each pillar and the benefits you accrue are directly tied to your residency status, employment type, and contribution history.
- Pillar I (Sodra): If you are legally employed or self-employed in Lithuania and making social security contributions, you are automatically accruing rights for Pillar I. The key is the length of your insurable period (stažas) and the amount of your contributions. Even if you only work in Lithuania for a few years, these contributions count. Lithuania has social security agreements with many countries, particularly within the EU/EEA, allowing for the aggregation of insurance periods. This means your years of contribution in, say, Germany or France could potentially count towards your eligibility for a Lithuanian pension, and vice-versa. Understanding these international agreements is complex but crucial.
- Pillar II (Funded Accumulation): Your participation in Pillar II is linked to your Pillar I contributions. If you're contributing to Sodra, you're either automatically enrolled or have the option to opt-in. The accumulated funds are yours, irrespective of where you eventually retire.
- Pillar III (Voluntary): As this is entirely voluntary, eligibility is mainly about being a tax resident in Lithuania to benefit from the tax deductions and having the disposable income to contribute. Your ability to sign up for these products usually requires an asmens kodas (personal code) and a Lithuanian bank account. How to Get Your Asmens Kodas (Personal Code) and Why It Matters for Healthcare is a good read, as the asmens kodas is vital for almost all administrative tasks, including setting up pension plans.
It's common for expats to overlook how short periods of work can impact future entitlements. Even a few years of contributions can build some rights, so it's worth understanding what you're entitled to before you leave.
Combining Pillars for a Secure Retirement
The real power of the Lithuanian pension system for expats lies in strategically combining the three pillars. Solely relying on Pillar I, especially if you haven't contributed for a significant portion of your career in Lithuania, is unlikely to provide a comfortable retirement.
Here’s how you might approach it:
- Foundation: Maximize your Pillar I contributions by ensuring you are always legally employed or correctly declaring your self-employment income to Sodra. This establishes your basic safety net.
- Growth Engine: Actively participate in Pillar II. Even if you were auto-enrolled, take the time to review your fund choice, consider your risk appetite, and perhaps even make additional voluntary contributions if your budget allows. The state contribution here is a valuable bonus.
- Personalization and Boost: Leverage Pillar III for additional savings and significant tax benefits. This is your chance to customize your retirement portfolio, choosing products that align with your long-term goals and risk profile. It's an excellent way to proactively save for the kind of retirement you envision, whether that's in Lithuania or elsewhere.
By combining all three, you create a diversified retirement strategy. You have the stability of the state pension, the growth potential of privately managed funds, and the flexibility and tax efficiency of personal savings.
| Pension Pillar | Nature | Contributions | Key Feature | Expat Consideration |
|---|---|---|---|---|
| Pillar I | Mandatory (State) | Employee + Employer (via Sodra) | Basic state pension, "pay-as-you-go" | Eligibility depends on contribution years; international agreements. |
| Pillar II | Semi-Mandatory (Funded) | Employee + State + Optional Personal | Individual funds managed privately, market-linked | Potential for higher growth, portability issues if leaving. |
| Pillar III | Voluntary (Private) | Individual | Tax incentives, full flexibility, private funds | Great for supplementing, tax deductions for residents. |
Portability and International Considerations
This is perhaps one of the biggest questions for internationally mobile professionals: what happens to my pension if I leave Lithuania?
- Pillar I: If you're an EU/EEA citizen and move to another EU/EEA country, your contribution periods in Lithuania will generally be recognized under EU social security coordination rules. When you retire, each country where you contributed will pay a portion of your pension based on the periods you worked there. If you move outside the EU/EEA, it depends on whether Lithuania has a bilateral social security agreement with that country. Without such an agreement, your contributions might remain "locked" in Lithuania until you reach the Lithuanian retirement age, and you'd need to claim it from abroad, which can be administratively challenging.
- Pillar II: The funds accumulated in your individual Pillar II account are yours. If you leave Lithuania, you generally can't simply transfer these funds to a pension scheme in another country immediately. Often, the funds must remain invested in Lithuania until you reach retirement age, at which point you would claim them. However, some pension accumulation companies might have provisions for transferring to certain international schemes, or you might be able to withdraw the funds as a lump sum under specific conditions (e.g., if the amount is very small, or after a long period of non-residency), though this often comes with tax implications. It is crucial to consult your specific fund provider and a financial advisor specializing in cross-border pensions.
- Pillar III: These are private investments. While you can't typically "transfer" them directly into another country's state pension system, you can often manage these investments from abroad or liquidate them. Again, tax consequences on withdrawal or liquidation will apply and depend on both Lithuanian tax law and the tax laws of your new country of residence. This is a prime area where services that help with Taxes in Lithuania for Expats, or specialists in international financial planning, become indispensable.
The overall takeaway here is not to assume seamless integration. While some agreements exist, especially within the EU, planning for your pension as an expat requires foresight and often professional advice to avoid losing out on hard-earned savings.
Important Considerations and Next Steps
Navigating the Lithuanian pension landscape, even with a clear understanding of the pillars, requires ongoing attention. Your circumstances might change, regulations might evolve, and your financial goals could shift.
Monitoring Your Pension
Keeping track of your pension contributions and accumulated savings is crucial. Fortunately, Lithuania has made significant strides in digitalizing administrative services:
- Sodra Portal: For Pillar I and your overall social insurance record, the Sodra online portal (www.sodra.lt) is your go-to resource. Once you have your electronic identification (like a Mobile ID or Smart-ID), you can log in and view your contribution history, accumulated work periods (stažas), and estimated future pension benefits. This is also where you can manage your Pillar II participation choices.
- Pension Fund Portals: For Pillar II and Pillar III (if you have opted for private pension funds), your chosen fund provider (e.g., Swedbank, Luminor, SEB) will have an online portal where you can monitor your investments, track performance, and view statements. Regularly checking these platforms is vital to ensure your funds are performing as expected and that your contributions are being correctly allocated.
Regularly reviewing your pension statements, ideally once a year, will help you stay informed and spot any discrepancies early. This proactive approach will save you headaches in the long run.
Seeking Professional Advice
While this guide provides a comprehensive overview, personal financial situations are unique. The complexities of international taxation, cross-border pension portability, and individual investment strategies mean that professional advice is often a worthwhile investment.
Consider consulting:
- Financial Advisors in Lithuania: Look for advisors who specialize in expat finances or international planning. They can help you assess your risk profile, choose appropriate Pillar II and III funds, and create a holistic retirement plan tailored to your stay in Lithuania and beyond.
- Tax Consultants: Especially if you have income or assets in multiple countries, or plan to move frequently, a tax consultant (such as those associated with the brand Taxes for Expats) can provide invaluable guidance on avoiding double taxation, maximizing deductions, and understanding the tax implications of pension withdrawals.
- Sodra and Pension Fund Representatives: Don't hesitate to reach out directly to Sodra or your chosen pension fund providers with specific questions about your contributions, eligibility, or fund performance. They are the primary source of factual information about their respective pillars.
Planning for retirement is a marathon, not a sprint. By engaging with the Lithuanian pension pillars proactively, monitoring your progress, and seeking expert advice when needed, you can build a robust financial future for yourself, no matter where your expat journey takes you.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, legal, or tax advice. While we strive to provide accurate and up-to-date information, the Lithuanian pension system and tax laws are subject to change. Expats are strongly advised to consult with qualified financial advisors, tax consultants, and the relevant official authorities (such as Sodra and the Lithuanian Tax Inspectorate – VMI) for personalized advice pertaining to their specific circumstances.